


Is Meta Stock Still a Buy After Borrowing About $25 Billion This Month?
Is Meta Stock Still a Buy After Borrowing About $25 Billion This Month?
Daniel Sparks, The Motley FoolMon, November 16, 2026 at 12:07 AM UTC
0
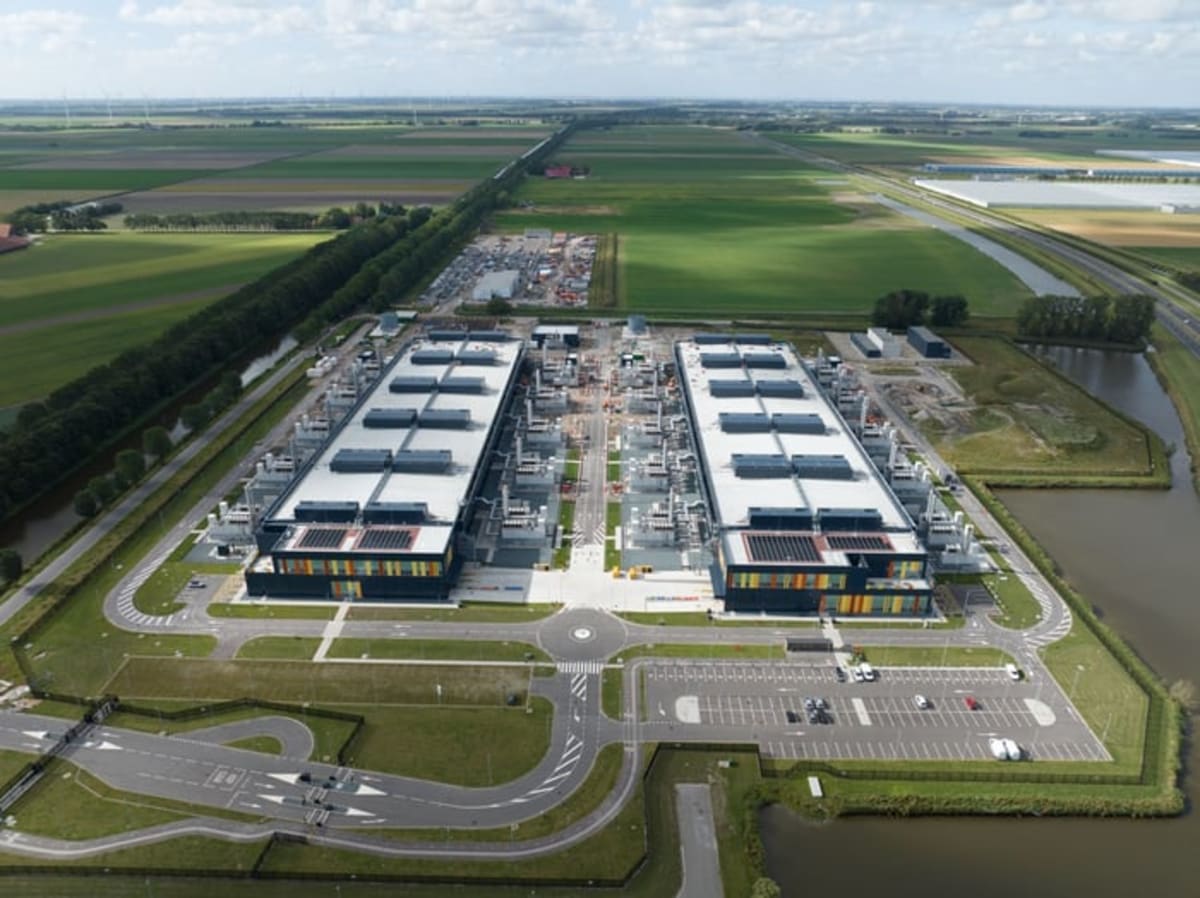
Image source: Getty Images.Key Points -
Meta priced $15 billion in dollar bonds on Nov. 3 and its first euro bonds, totaling €9 billion, on Nov. 4.
Free cash flow went negative in the third quarter as capital spending hit $34.9 billion.
The stock costs around 18 times the earnings expected for 2027.
Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Meta Platforms (NASDAQ:META) has been raising money quickly. In late October, it priced a stock sale at $625 a share along with a sale of mandatory convertible preferred stock. Next, the social media company sold $15 billion in dollar bonds on Nov. 3 and €9 billion in euro bonds (around $10 billion) on Nov. 4. The euro deal was its first.
Meta borrowed about $25 billion this month. And the stock trades near $640 as I write, about 18% below its Sept. 24 closing high of about $778.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Is Meta stock still a buy with the extra debt? I think so, but the borrowing comes right before what might be Meta's most expensive quarter yet.
What's the money for?
Meta said it plans to use the proceeds for general corporate purposes. Much of it will probably go toward the servers, data centers, and network infrastructure behind its capital spending.
Showing how quickly that spending has risen, Meta's capital expenditures (including principal payments on finance leases) climbed from $19.8 billion in the first three months of 2026 to $31.1 billion in the second quarter and $34.9 billion in the third quarter. Operating cash flow, meanwhile, stayed at around $32 billion to $33 billion every quarter. So, free cash flow (the cash left after capital spending) dropped from $12.4 billion in Q1 to $784 million in Q2 and then to negative $2.1 billion in Q3.
And the biggest spending quarter is probably still ahead. Management expects 2026 capital expenditures of $135 billion to $145 billion. With around $85.8 billion spent through September, the guidance points to another $49 billion to $59 billion by year-end.
If fourth-quarter operating cash flow comes in near the third quarter's $32.8 billion, Meta's spending could top it by about $16 billion to $26 billion. The new bonds raised around $25 billion after fees, plus about $14.3 billion from the preferred stock, which pays a 6.5% annual dividend.
Together, these amounts exceed a quarter's shortfall, and more is coming. Meta won't get the roughly $28.7 billion from its common stock sale until forward sale agreements settle, by Nov. 19, 2027, at the latest. Of course, management has said it plans to keep "investing aggressively" next year, too.
The interest bill is climbing but Meta can afford it
Meta owed $59 billion in notes at the end of 2025, and that face value rose to $84 billion by Sept. 30 after a $25 billion bond deal in May. This month's bonds bring it to around $109 billion.
Borrowing has gotten pricier, too. The new dollar notes pay interest rates of 5.85% (due 2031) to 7.5% (due 2056). Even the lowest beats the highest rate on any Meta bond sold before 2026, which was 5.75%.
The euro notes came in lower, at 4.3% to 6.4%, partly because benchmark interest rates in Europe sit below those in the U.S.
On Meta's third-quarter earnings call, chief financial officer Susan Li said the new Class C stock was part of a push "to ensure that we have access to a diverse pool of funding sources."
Advertisement
In the third quarter, Meta's interest expense more than quadrupled year over year to $977 million, and the new bonds add about $1.5 billion annually.
I think Meta can cover that bill. After all, it generated $22.9 billion in operating income in the third quarter alone, not counting a $9.89 billion legal charge. And Moody's still rates the debt Aa3 with a stable outlook, but S&P Global's AA- rating has a negative one.
Still a buy at about $640?
Meta's ad revenue, which pays for all this, climbed 26% year over year to $63.1 billion in the third quarter. Total revenue growth has slowed, from 33% in Q1 to 28% and then 26%. But management expects fourth-quarter revenue between $73 billion and $76 billion, indicating growth of about 22% to 27%.
And the stock doesn't look expensive. At roughly $640, Meta trades at about 18 times the earnings expected for 2027, near the 17.7 times forward earnings FactSet put on the S&P 500 on Nov. 5. So investors are paying about a market-average price for a company growing revenue over 20%.
Spending could outrun cash for longer than investors think, of course, and more borrowing at 6% to 7.5% could follow.
In the end, I think the extra debt is a fair cost for a business growing so fast, and the shares look worth buying around $640. I'd just want to see free cash flow go positive again once this round of spending peaks.
Should you buy stock in Meta Platforms right now?
Before you buy stock in Meta Platforms, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Meta Platforms wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $335,171!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,000,640!*
Now, it’s worth noting Stock Advisor’s total average return is 823% — a market-crushing outperformance compared to 208% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 15, 2026.
Daniel Sparks and his clients do not have positions in any of the stocks mentioned. The Motley Fool has positions in and recommends Meta Platforms. The Motley Fool has a disclosure policy.
Source: “AOL Money”
